IMF urges action to avert fiscal crisis
Gap widening between tax revenues and governments’ ambitious development targets
The International Monetary Fund has warned that governments worldwide are facing mounting fiscal pressures as public debt remains elevated, interest rates stay high and budget deficits continue to widen despite a relatively resilient global economy.
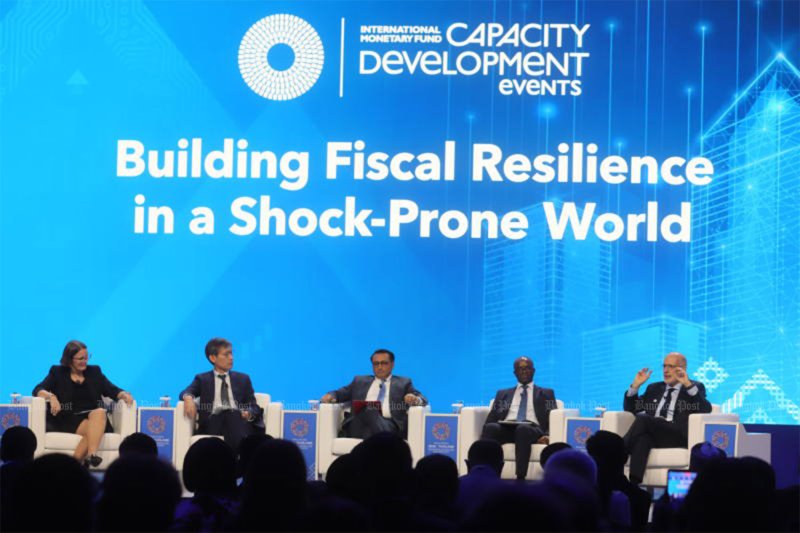
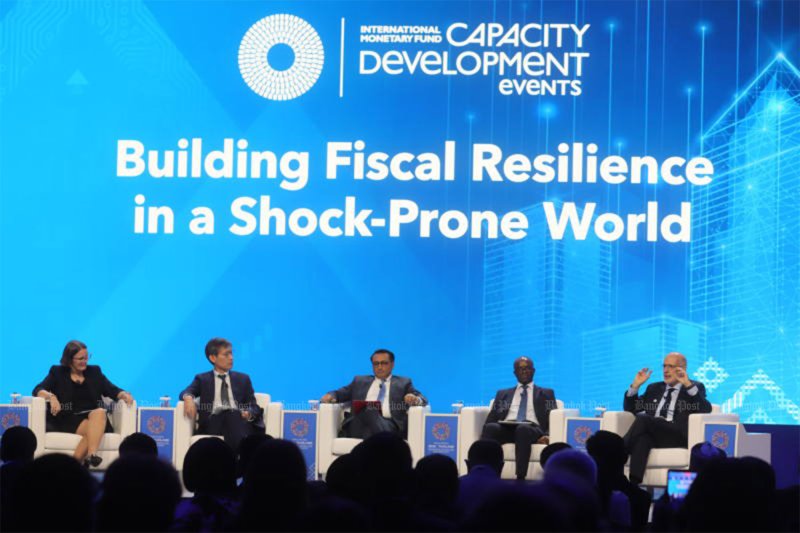
Rodrigo Valdés, director of the IMF’s Fiscal Affairs Department, said fiscal challenges have become significantly more acute than just a few years ago, with deficits in many countries expanding rather than narrowing as expected.
Mr Valdés identified the lack of meaningful action to rein in fiscal deficits and persistently high interest rates as two major concerns for policymakers.
He noted that while similarly high interest rates were present 15 or 20 years ago, public debt levels were considerably lower at that time.
“The current combination of high public debt and elevated interest rates is creating mounting challenges for policymakers worldwide,” he said on Thursday at the IMF-World Bank annual meetings in Bangkok.
“High benchmark interest rates in major advanced economies are also generating significant spillover effects, forcing emerging markets to contend with rising borrowing costs alongside domestic economic pressures.”
“Public finances are facing further strain from external shocks, including volatile energy and food prices, declining official development assistance and heightened geopolitical uncertainty.”
He also highlighted the widening gap between national tax revenues and governments’ ambitious development targets, noting that countries with tax revenues of around 10% of GDP (the figure for Thailand is 17%) would struggle to finance essential infrastructure, healthcare and education at the scale required.
Rather than making hasty tax cuts to stimulate short-term growth, Mr Valdés advocated smarter tax policy design.
By restructuring tax systems, governments can foster sustainable economic growth without sacrificing the revenue streams necessary to finance public investment and maintain fiscal stability.
With fiscal resilience wearing thin, avoiding a full-blown fiscal crisis has become an urgent global priority, he said, urging policymakers to act immediately to strengthen fiscal institutions, optimise public spending and mobilise domestic revenues.
Building robust fiscal capacity, supported by international partnerships and technical assistance, remains vital for both advanced and developing economies to weather future economic shocks and secure sustainable, long-term growth, he said.
Source – Bangkok News